In this article
01/03Good structuring starts with the commercial objective, not the jurisdiction, bank or product.
01
Navigating the Debt Landscape in the UAE
Obtaining credit or corporate financing in the UAE is highly rewarding but requires a meticulous, structured presentation of financial records. UAE banks look for low-risk profiles, stable operations, and clear repayment capability.
A business loan can fuel your inventory expansion, regional capital expenditure, or working capital needs. Having a solid compliance pack prepared beforehand will increase your probability of success by over 80%.
02
Primary Corporate Documentation
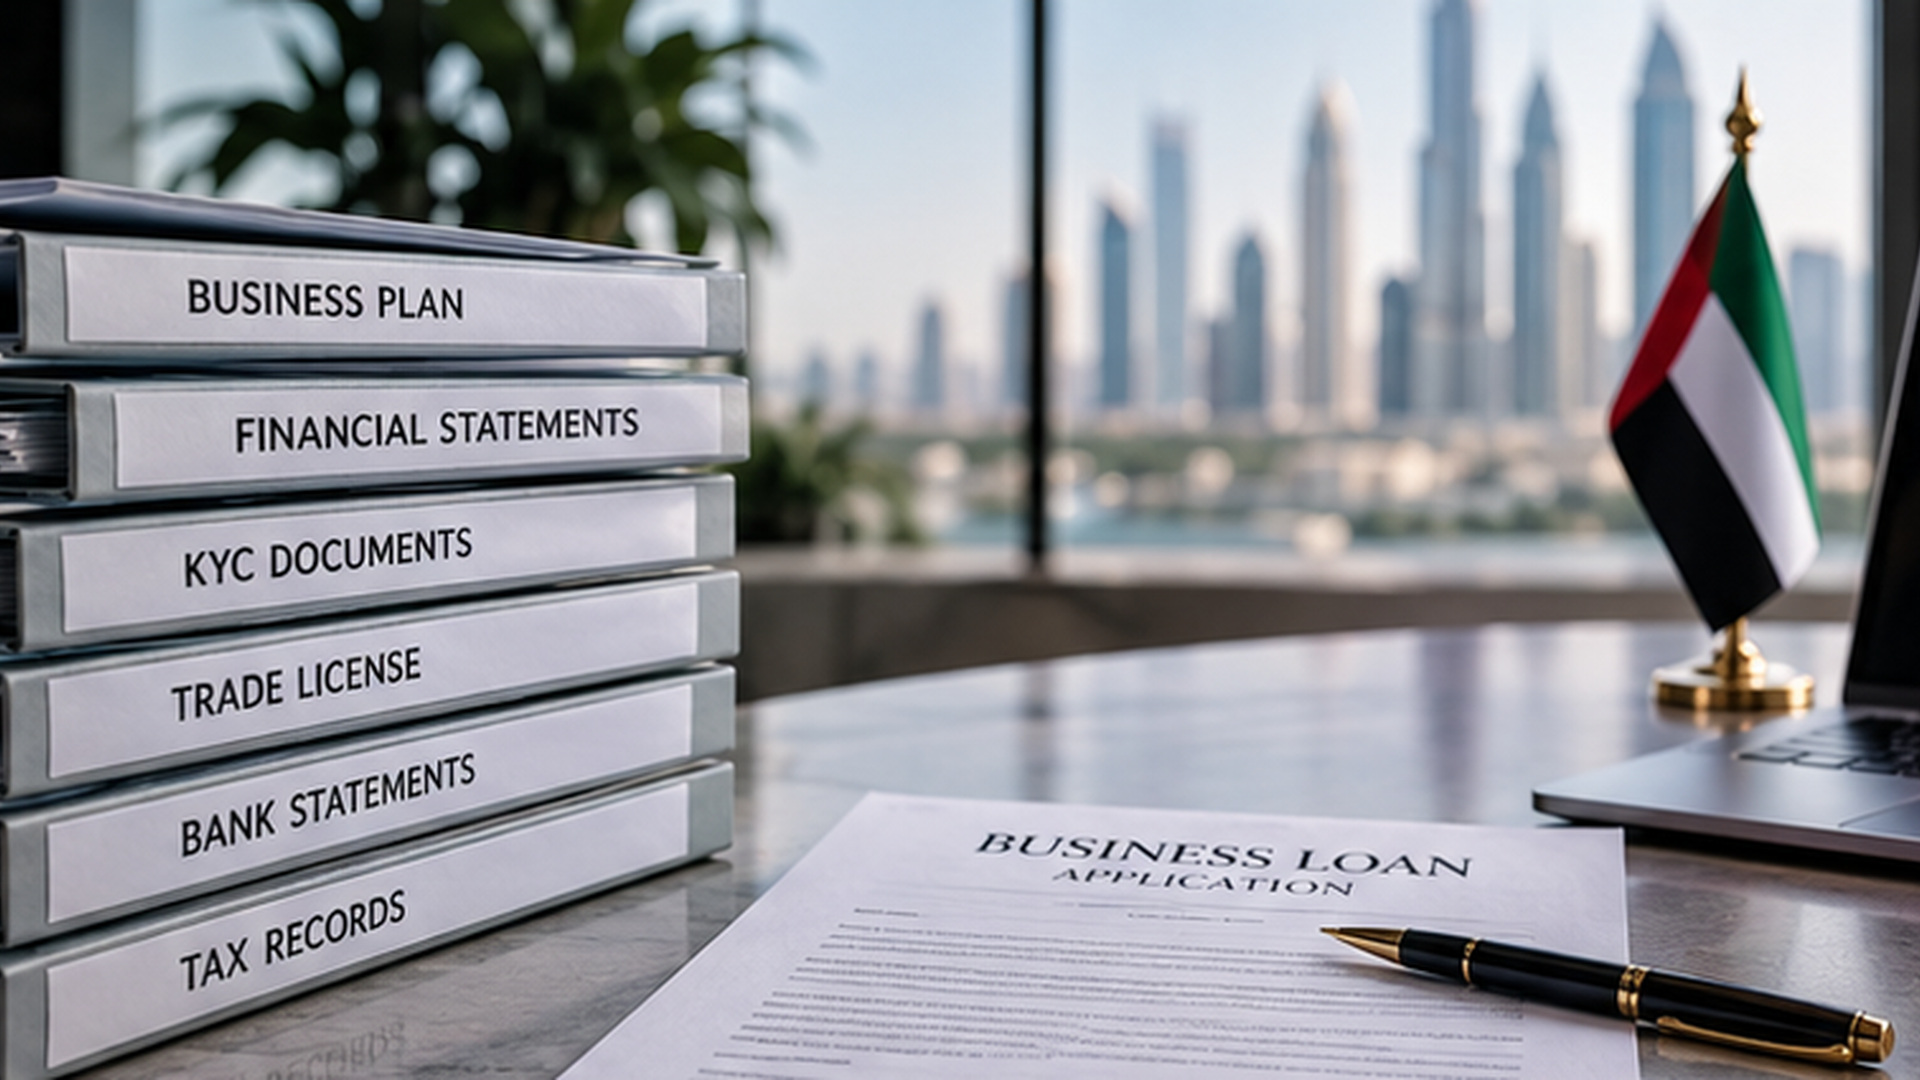
To initiate any loan application, you must provide your active Trade License (issued by Free Zone authorities or Mainland DED), Certificate of Registration, Memorandum of Association (MOA), and Article of Association (AOA).
Furthermore, clear corporate hierarchy documents showing shareholder breakdown and Ultimate Beneficial Owner (UBO) declarations are mandatory.
03
Financial Records and Bank Statements
UAE lenders will request audited financial statements for the past 2 years, showing stable revenue progression. Crucially, you must submit original bank statements for the past 6 to 12 months.
Banks check for healthy cash margins, minimal bounced cheques, transaction consistency, and that the account is operated under the applicant company's trade name.