In this article
01/03Good structuring starts with the commercial objective, not the jurisdiction, bank or product.
01
The Modern Compliance Hurdles
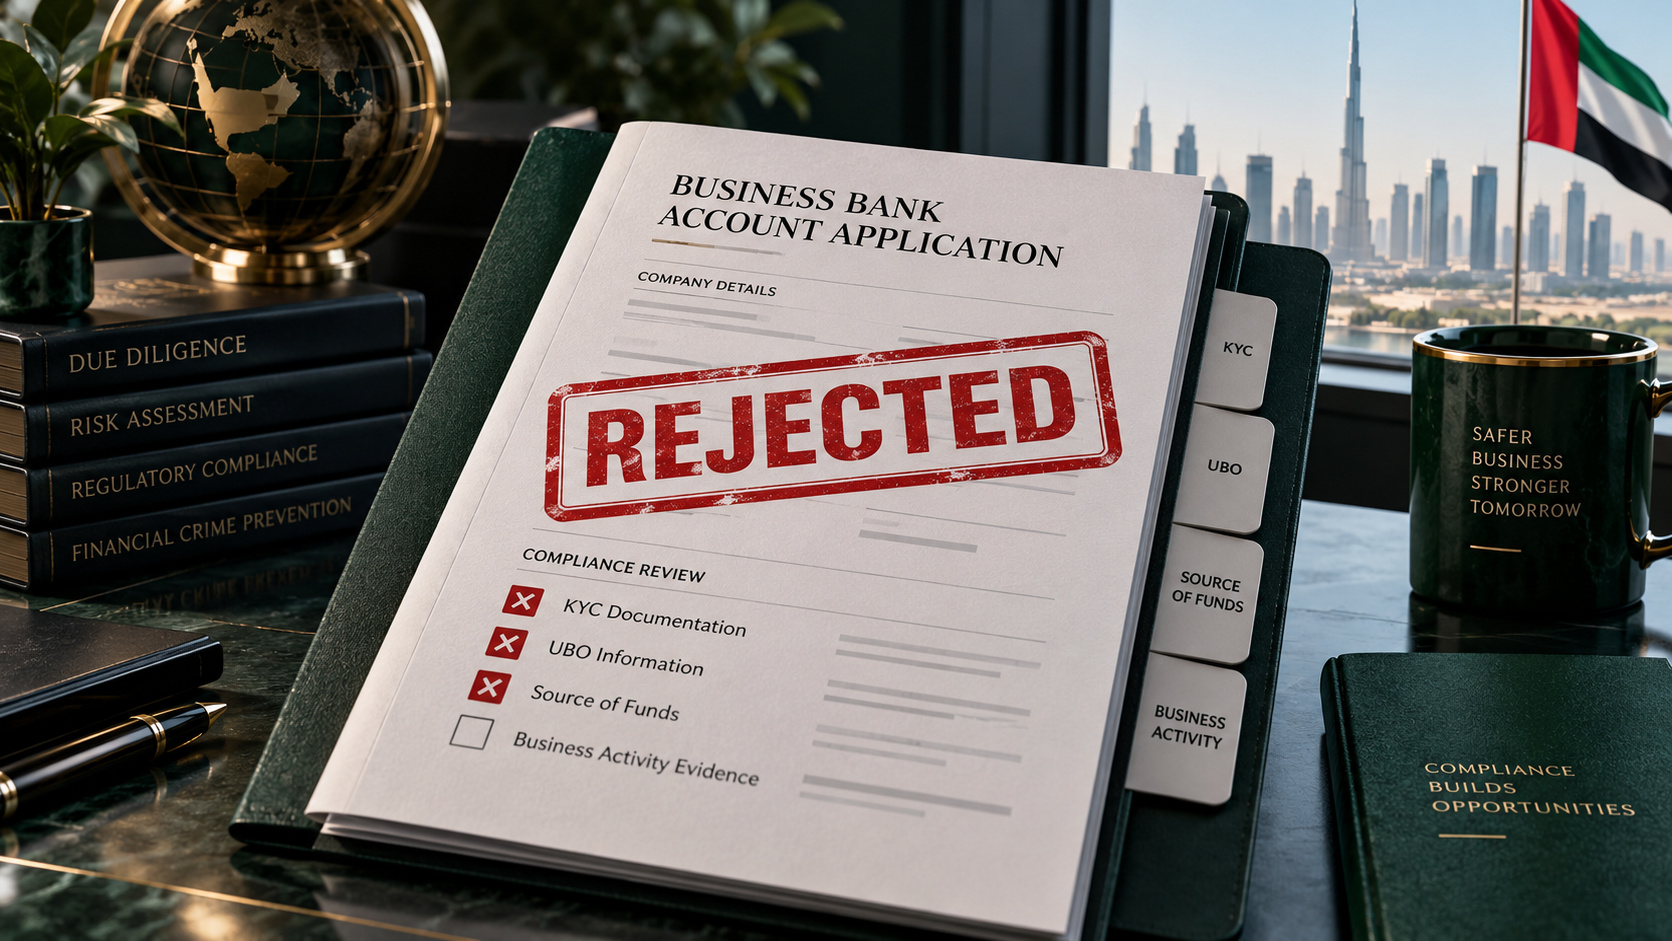
Opening a corporate bank account in the UAE has transitioned from a straightforward paperwork exercise to a rigorous compliance check. Under AML (Anti-Money Laundering) and CTF guidelines, banks are legally bound to investigate every business's origin of capital, operational substance, and UBO profile.
Many entrepreneurs find their account applications rejected without any specific reason given. Understanding these reasons from the banker's perspective is the key to getting approved.
02
Top Reasons for Account Rejection
Lack of Physical Substance: Post-pandemic, operating solely with virtual offices or 'flexi-desks' without physical rental contracts is flags as high-risk by major tier-1 UAE banks.
Vague Business Activities: If your website, invoice structure, or business plan describes a generic or complex trade pattern (e.g. general trading across multi-sectors), banks struggle to categorize your AML risk.
High-Risk Jurisdictions: Having UBOs, major suppliers, or target markets located in sanction-flagged or grey-listed countries will trigger immediate application rejection.
03
Strategic Fixes for a Successful Application
Start by building a professional KYC Pack. This should include detailed customer/supplier draft agreements, clear CVs showing shareholder experience in the designated industry, and physical office leases.
Partnering with a banking advisor like Orpheus ensures your dossier is structured correctly, matching your activities only to banks with matching risk-appetites.